


 CryptoSlate
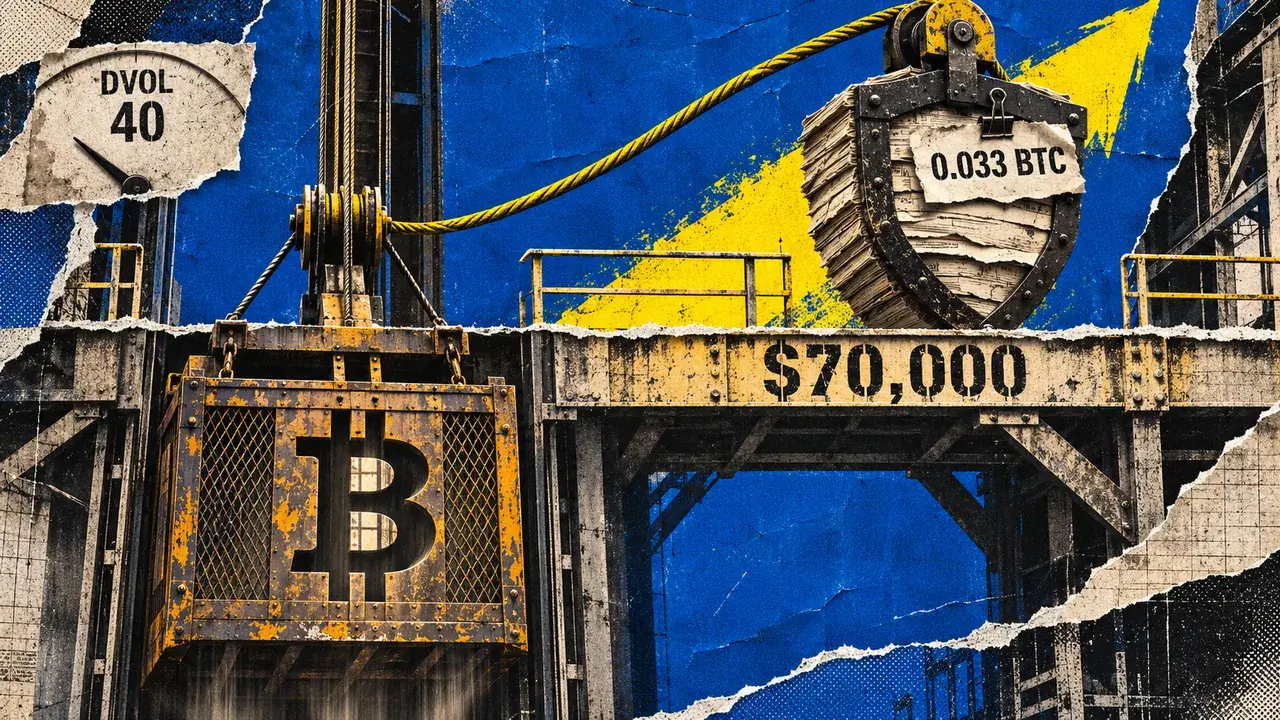
The cost of hedging Bitcoin with a $70,000 strike more than doubled in a single day. Deribit's November 27 $70,000 put traded at 0.0145 BTC at 11:51 UTC on November 12 and 0.033 BTC at 10:15 UTC on November 13, a 127.6% increase in BTC terms. Yet the implied volatility attached to those executions actually fell, from 38.97% to 37.67%. Bitcoin's index price dropped from $72,805.71 to $69,320.08 over the same window, taking spot from above the strike to below it. For a new buyer near 10:40 UTC on November 13, the ask worked out to roughly $2,319.74 per one-BTC contract before fees.
Why it matters
The move is a mechanical lesson in how inverse options are priced. A protective put at a fixed dollar strike gains value as the underlying falls toward and through that strike, so the same hedge can double in cost without any rise in volatility. Converting each trade at its own contemporaneous index gives dollar equivalents of about $1,055.68 and $2,287.56, a 116.7% increase, confirming the repricing came from the strike mechanics rather than the currency of the quote.
Deribit's broad DVOL gauge hovered near 40 across the window, and a CryptoQuant analysis placed the reading of 40.77 well under its 77.8 median for days when Bitcoin sat at least 17.4% below its rolling 30-day high. The historical framing matters: hedges repriced sharply in a subdued vol regime, not during a volatility spike.
Market impact
For holders rolling fixed-strike protection, the immediate consequence is already priced in: the hedge bill climbs precisely as Bitcoin falls, and a $70,000 strike does not promise a $70,000 net sale once premiums, fees, delivery costs and settlement references are netted out. The two observations landed ahead of October's PPI release at 13:30 UTC, a clean checkpoint for watching whether put premiums keep inflating or DVOL finally catches up to the spot slide.

Frequently asked questions
-
Why did the Bitcoin put hedge double in cost while implied volatility fell?
The put's fixed $70,000 strike gained value as Bitcoin's index price fell from $72,805.71 to $69,320.08, moving from above the strike to below it. The underlying price, not volatility, drove most of the premium increase.
-
How much does the November 27 $70,000 Bitcoin put cost a new buyer?
At 10:40 UTC on November 13, the order book showed a 0.0335 BTC ask, which equaled about $2,319.74 per one-BTC contract before fees at an index price of $69,245.85.
-
What is DVOL and why doesn't it capture this hedge cost?
DVOL is Deribit's forward-looking annualized implied volatility index covering 30 days across strikes and expiries. The November 27 put had roughly 14 days remaining, so the broad index and the shorter-dated contract describe different exposures.
-
Does the $70,000 strike guarantee a $70,000 net sale price?
No. The buyer pays the BTC premium upfront, and trading fees, delivery fees, currency conversion and the settlement reference all affect the net result. An in-the-money inverse put settles through an inverse futures contract into BTC at expiry.
-
How does the current DVOL reading compare to history?
A CryptoQuant analysis reported DVOL at 40.77 against a median of 77.8 across 290 daily closes since March 2021 when Bitcoin was at least 17.4% below its rolling 30-day high, with a median of 49.9 for qualifying 2026 observations.
 WuBlockchain
 Lookonchain
 TheBlock
 WatcherGuru
 CoinDesk