








 CryptoSlate

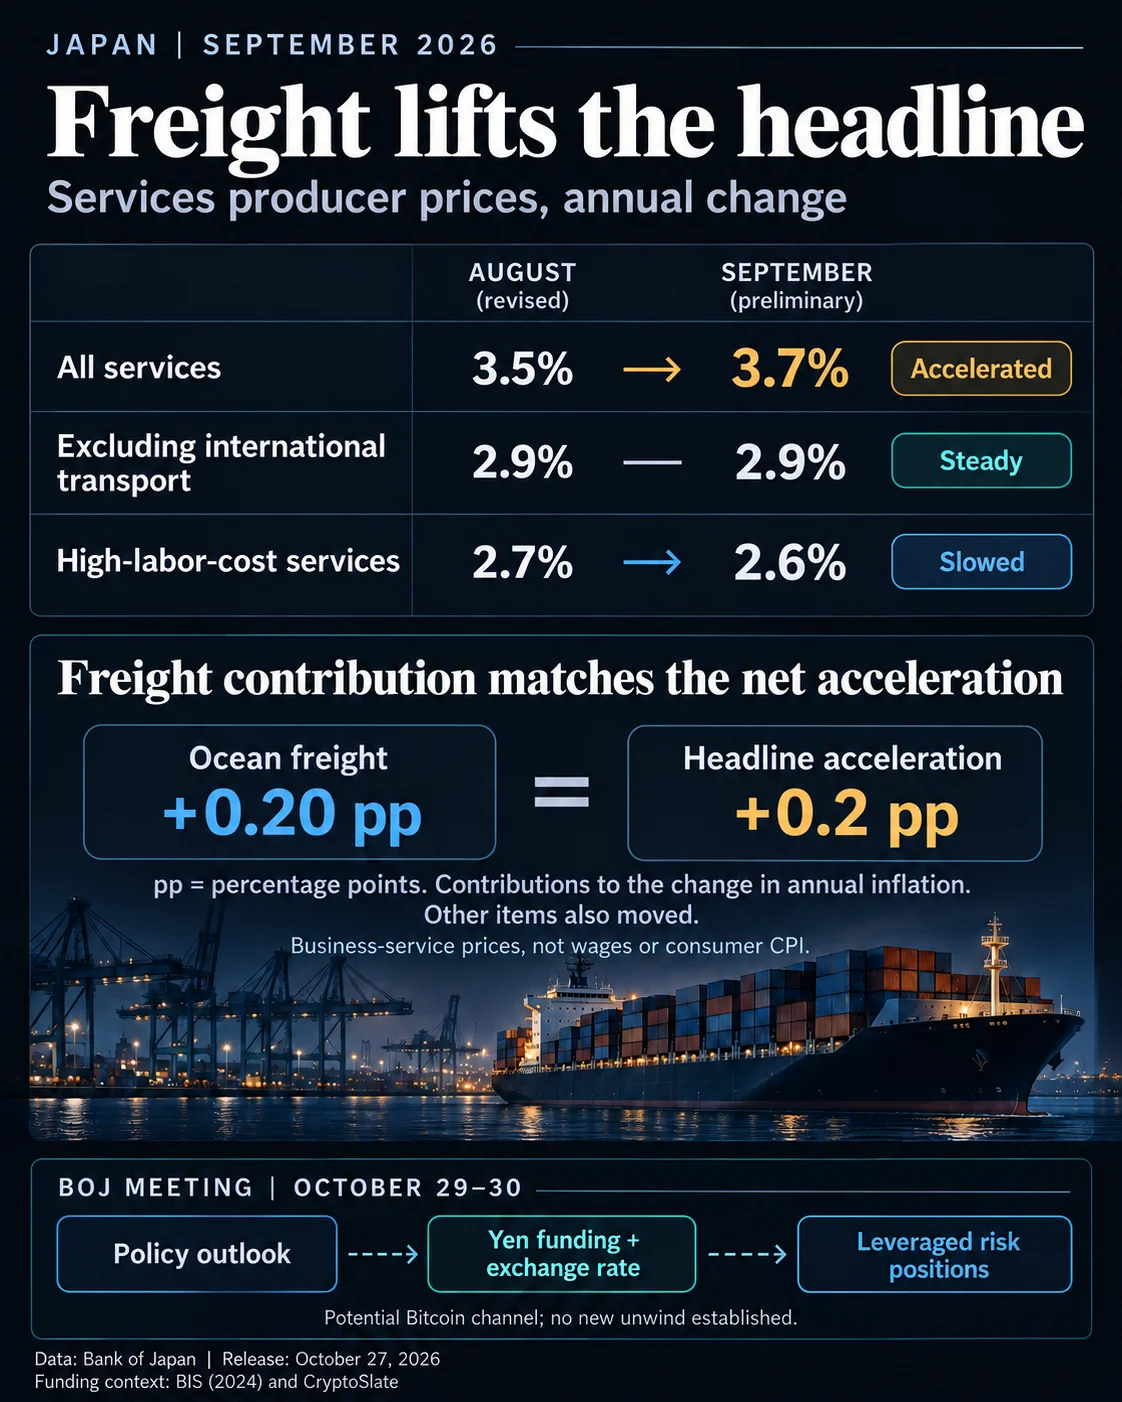

Japan’s services producer inflation accelerated to 3.7% in September from a revised 3.5% in August, but the details point in different directions before the Bank of Japan’s October 30 decision. Inflation excluding international transportation held at 2.9%, while high-labor-cost services price growth eased to 2.6% from 2.7%.
Ocean freight contributed 0.2 percentage points to the headline acceleration. The Services Producer Price Index measures prices charged to businesses and governments, rather than consumer inflation, so the labor-cost reading tracks selling prices instead of employee pay. Separate data showed scheduled cash earnings rose 3.8% year over year in August across all employment types at establishments with at least five employees.
Why it matters
The mixed services data complicates the BOJ’s policy signal. The bank’s underlying-inflation framework weighs the breadth of consumer price increases alongside labor tightness, the output gap, inflation expectations and wage growth. Its September 18 decision kept the overnight call-rate target around 1.25%, while retaining a path toward further increases tied to economic and financial conditions.
For markets, the key question is whether Friday’s policy statement and Outlook Report strengthen expectations for higher Japanese short-term rates. A tighter-than-expected path could lift borrowing costs for positions financed with yen and support yen appreciation, increasing repayment costs in other currencies.
Market impact
Those conditions could pressure leveraged investors to reduce risk, with Bitcoin exposure vulnerable if yen strength coincides with independently observed deleveraging across risk assets. The BIS has documented how leveraged equity and currency unwinds, higher margin requirements and deleveraging can amplify volatility, but that historical analysis does not quantify current yen-funded Bitcoin positions or establish a new unwind.
The bearish case therefore remains conditional. Stronger pricing for higher Japanese rates, a firmer yen and broad risk-asset deleveraging would make the warning more credible. Yen weakness or stable funding would weaken it.

Frequently asked questions
-
What happened to Japan’s services producer inflation in September?
Headline services producer inflation rose to 3.7% from a revised 3.5% in August. Inflation excluding international transportation stayed at 2.9%.
-
Why is the BOJ decision difficult to read from the services data?
Freight pushed the headline rate higher, while high-labor-cost services inflation eased to 2.6% from 2.7%. The opposing signals complicate the policy read.
-
What is the BOJ’s current overnight call-rate target?
The BOJ’s September 18 decision kept the overnight call-rate target around 1.25%. The bank retained a path toward further increases based on economic and financial conditions.
-
How could a tighter BOJ policy path affect Bitcoin exposure?
Higher Japanese borrowing costs and a stronger yen could make yen-funded positions more expensive to maintain and repay. That could pressure leveraged investors to reduce Bitcoin exposure.
-
What would confirm the bearish risk signal for Bitcoin?
The warning would be stronger if markets priced higher Japanese short-term rates while the yen strengthened and independent data showed deleveraging across risk assets. Yen weakness or stable funding would weaken the case.
 CoinTelegraph
 WatcherGuru
 Altcoin Daily
 Lookonchain
 Crypto News