








 CryptoSlate


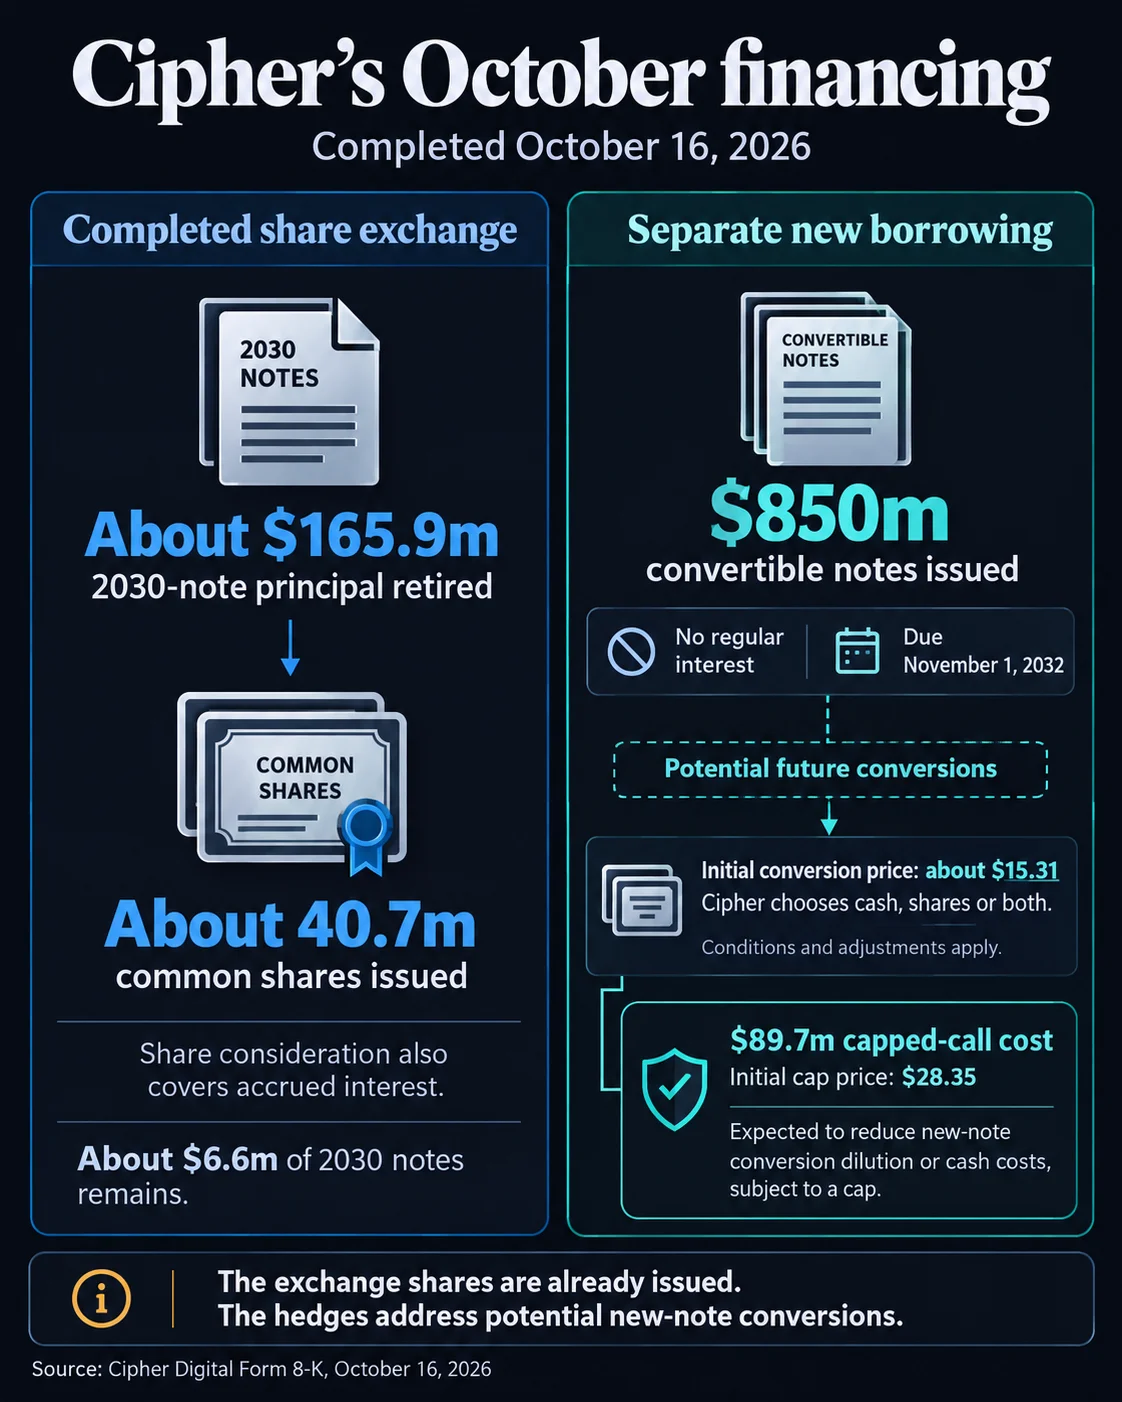
Cipher Digital shares closed at $8.98 on Oct. 16, down 10.6% on the session and at their lowest level since September 2025, extending a one-year decline of more than 52%. The same day, the Bitcoin miner completed a $850 million zero-coupon convertible bond offering and separately exchanged about $165.9 million of its convertible notes due 2030 for 40.7 million newly issued common shares, cutting that series to roughly $6.6 million outstanding. Together, the transactions leave the company with about $684 million more in outstanding debt principal and a meaningfully larger share base.
Why it matters
Cipher is trying to trade its dependence on Bitcoin mining for recurring lease revenue from high-performance computing infrastructure, and the financing math shows how capital-intensive that transition has become. The company reported about $25 million in second-quarter revenue against a $30 million adjusted EBITDA loss, a gap that makes external funding the engine of the entire buildout. The new notes carry no regular interest, but their initial conversion price of about $15.31 sits far above the market, and Cipher spent roughly $89.7 million on capped-call transactions extending dilution protection to $28.35.
The structural risk is the repayment right: investors in the new notes can demand cash in November 2030, well before the scheduled 2032 maturity, potentially forcing a large refinancing while the AI portfolio is still ramping.
Market impact
The dilution landed into an already sharp selloff, with roughly 31% of Cipher's market value per share erased since Oct. 12. Bondholders who received shares in the exchange could add further selling pressure if they liquidate or unwind hedging positions tied to the original debt.
The bull case still has one concrete data point: Cipher began delivering capacity at its Black Pearl data center in August, two months ahead of schedule, triggering initial rental payments from its hyperscale tenant. Construction continues at Barber Lake and Stingray. The stock now trades on whether that rental income scales fast enough to carry the debt before the 2030 repayment window opens.

Frequently asked questions
-
How much new debt did Cipher take on in the October transactions?
Cipher completed a $850 million zero-coupon convertible bond offering due November 2032. Combined with the note exchange, the two deals left the company with about $684 million more in outstanding debt principal.
-
Why did Cipher issue 40.7 million new shares?
The shares were issued to exchange approximately $165.9 million of its convertible notes due 2030, including consideration for accrued interest. That series was cut to roughly $6.6 million outstanding, but existing investors were diluted.
-
When can holders of the new convertible notes demand repayment?
Under specified conditions, investors can demand cash repayment in November 2030, four years before the notes' scheduled November 2032 maturity, which could create a substantial refinancing obligation.
-
What do Cipher's capped-call transactions cover?
Cipher spent approximately $89.7 million on capped calls to limit dilution from future conversions, with protection extending to an initial share price of $28.35 versus the notes' $15.31 conversion price.
-
How is Cipher's AI data center business performing so far?
Cipher reported about $25 million in second-quarter revenue and a $30 million adjusted EBITDA loss. Its Black Pearl data center began delivering capacity in August, two months ahead of schedule, triggering initial rental payments from its hyperscale tenant.
 Crypto News
 WuBlockchain
 Lookonchain
 TheBlock
 CoinTelegraph