


 CoinDesk
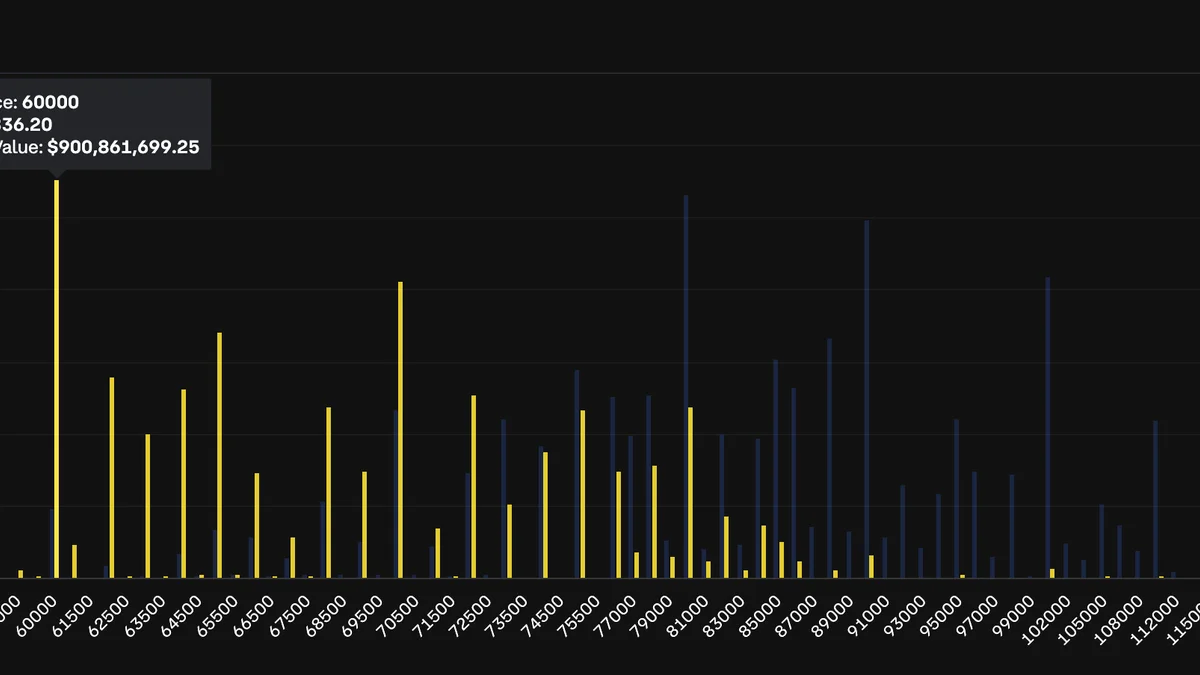


Bitcoin’s $60,000 put now carries $900 million in notional open interest on Deribit, making it the exchange’s largest options position. It has overtaken the $100,000 call, which stands at $867 million after traders sold back bullish positions. Bitcoin’s implied volatility also surged before easing, highlighting the market’s elevated concern over near-term price turbulence.
Why it matters
The change in Deribit’s largest options position points to heavier demand for protection around a Bitcoin decline. Paradigm’s Nicolas Quatravaux said traders bought large volumes of the $60,000 put during market weakness in February, March and June. SignalPlus also observed demand for multi-legged put strategies, while Volmex’s Bitcoin volatility index reached its highest level since June.
Open interest is a stock rather than a flow, however. It reflects positions accumulated over time and does not show where traders are adding risk today. The $100,000 call lost the top spot mainly because positions were unwound, with about 6,700 BTC of those calls sold back in October after more than 12,000 BTC were bought in September.
Market impact
Paradigm’s latest flow was dominated by one large participant rolling a put position toward lower strikes as Bitcoin declined. The position moved from a $74,000 strike in late October through $72,000, $68,000, $65,000 and finally $63,000 by the end of November, representing more than $1 billion in put blocks over two days.
That positioning leaves the market more sensitive around $60,000. At that level, two-way trading becomes more active, including smaller $60,000 and $64,000 put spreads. Volmex’s 30-day implied volatility index climbed to 57.13 on Sunday before retreating to 44, suggesting the initial shock has eased while hedging demand remains elevated.

Frequently asked questions
-
Does the largest open-interest put prove traders expect Bitcoin below $60,000?
No. Open interest is a stock accumulated over time, not a measure of current trading. Much of the $60,000 positioning was built during earlier periods of market weakness.
-
Why did Bitcoin’s $100,000 call lose the top options position?
The call lost its lead mainly because traders closed positions, not because a wave of new put buying displaced it. Paradigm recorded about 6,700 BTC of the calls being sold back in October.
-
How high did Bitcoin’s implied volatility index rise?
Volmex’s 30-day Bitcoin implied volatility index reached 57.13 on Sunday, its highest since June. It later eased to 44 as the initial market stress subsided.
-
What did the recent put ratio backspread involve?
One participant bought 750 BTC of $68,000 puts and sold 500 BTC of $72,000 puts, both expiring November 27. SignalPlus listed approximate expiry break-even prices of $62,380 and $70,650.
-
Which Bitcoin options strikes saw the most recent large positioning?
Paradigm saw a large put position roll from $74,000 through several lower strikes to $63,000. Around $60,000, activity shifted toward smaller two-way $60,000 and $64,000 put spreads.
 WuBlockchain
 Lookonchain
 CryptoSlate
 Whale Alert
 TheBlock