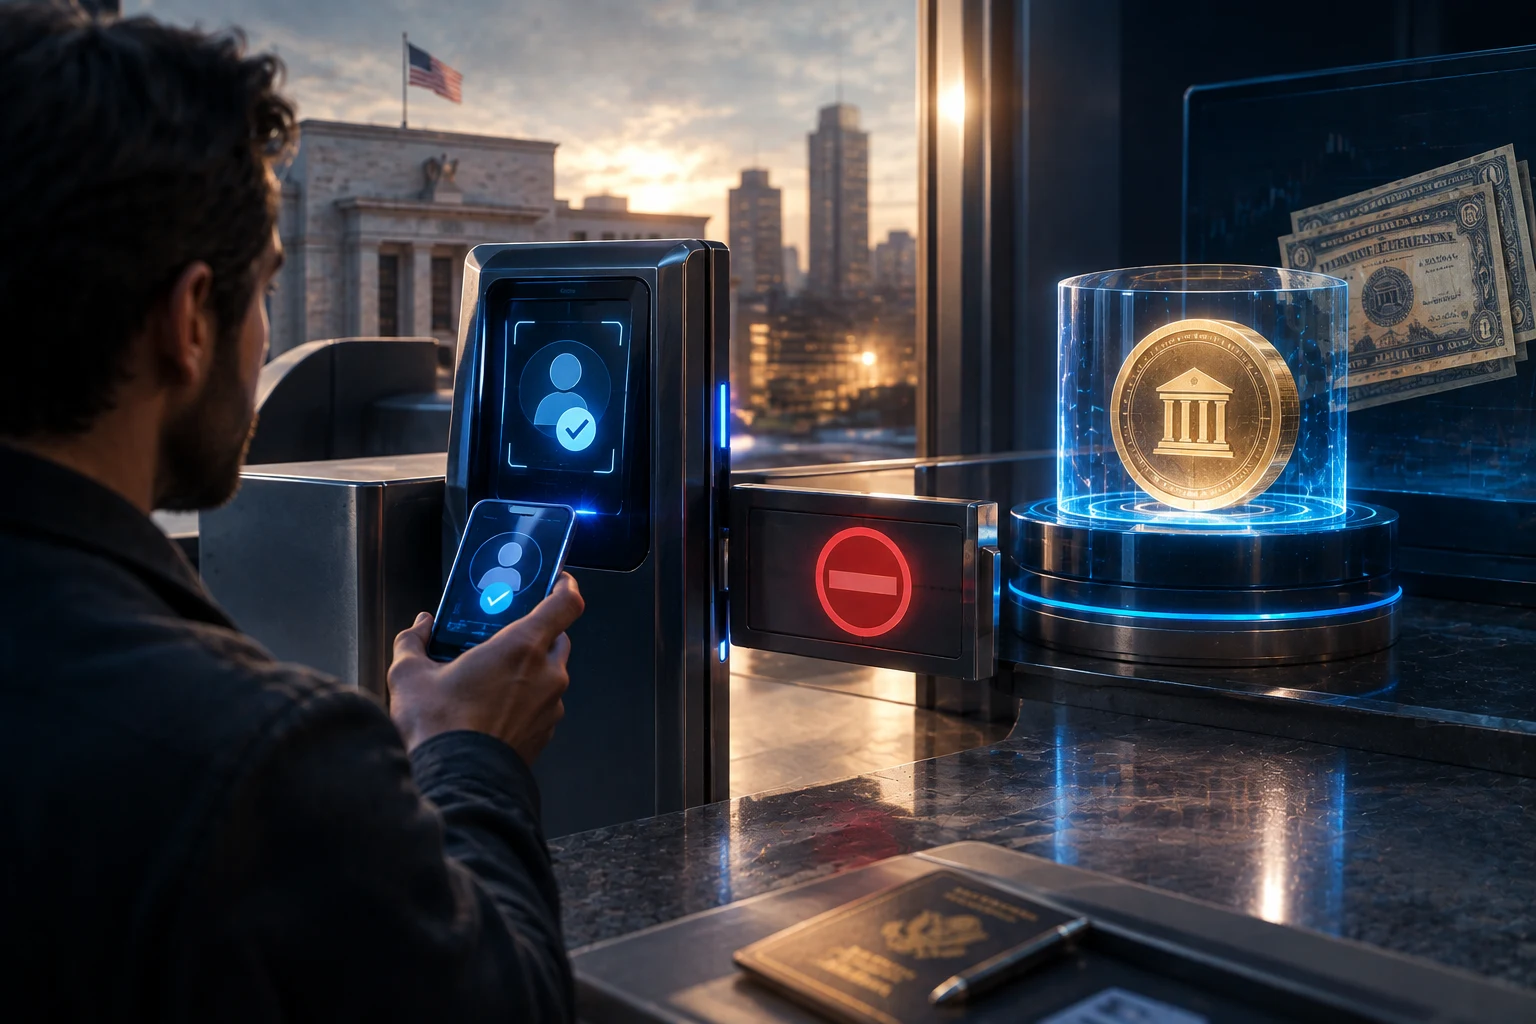
What "RWA KYC gating" actually means
The phrase rwa kyc gating describes a stack, not a single gate. On the surface, a tokenized U.S. Treasury fund looks like any other Ethereum, Arbitrum, Avalanche, or Solana asset: an address holds a balance, a wallet can sign a transfer, a DEX or aggregator can quote a price. Under the surface, three separate parties have to agree that the holder is allowed to be one.
The first party is the issuer, usually a registered investment adviser or a special-purpose vehicle. The second is the transfer agent, which maintains the official shareholder list and runs the identity checks. The third is the smart contract itself, which holds an on-chain whitelist of approved addresses and refuses to move tokens to anyone outside that list. If any of the three says no, the trade does not settle, regardless of how the wallet behaves.
This is why a user can hold ETH or USDC without ever proving who they are, yet cannot receive BUIDL or OUSG without documents. The gating is not a marketing choice by the protocol. It is the legal price the issuer pays to distribute the product in the United States without registering it as a public security offering.
The two U.S. exemptions that shape almost every tokenized treasury
The reason tokenized treasury funds look so similar to one another is that they are usually issued under one of two SEC exemptions: Reg D 506(c) for U.S. investors, or Reg S for offshore investors. Both carve out a path that avoids a full public registration, and both come with hard limits on who is allowed in.
Reg D 506(c): accredited investors only
Under Rule 506(c) of Regulation D, an issuer can raise an unlimited amount of money from accredited investors without registering the offering with the SEC, provided it takes reasonable steps to verify that every buyer is, in fact, accredited. General solicitation is allowed, which is why you see these products advertised on crypto podcasts and YouTube, but the underlying buyer pool is closed to retail.
An accredited investor in the U.S. is someone with an individual income above $200,000 in each of the last two years, or joint income above $300,000, or a net worth above $1 million excluding the primary residence, or a specific professional license. BUIDL from BlackRock, OUSG from Ondo, USYC from Circle's Hashnote, JTRSY from Janus Henderson, and USTB from Superstate are all distributed this way to U.S. persons. The issuer, or a third-party verification vendor, has to keep the accreditation evidence on file, and that file is what the transfer agent relies on when it approves the on-chain mint.
The key detail most readers miss: 506(c) verification is not a one-time wallet check. If the holder wants to move tokens to a new address, the new address has to be added to the whitelist first. If the holder wants to redeem, the redemption address has to match. If the holder transfers tokens by mistake to a non-whitelisted address, those tokens are effectively frozen until the new holder goes through the same accreditation process. The smart contract enforces this even when the user does not realize it has happened.
Reg S: open to non-U.S. persons, closed to U.S. persons
Regulation S is the offshore counterpart. It lets an issuer sell securities outside the United States to non-U.S. persons without registering with the SEC. The product you see on-chain is the same economics, but the eligible buyer pool is the inverse of 506(c): U.S. persons are explicitly excluded.
USDY from Ondo is the clearest example. USDY is marketed to a global crypto-native audience and is widely listed across Arbitrum, Solana, and other chains, yet its subscription flow requires the buyer to attest that they are not a U.S. person and to pass the issuer's KYC. The attestation is backed by document checks, IP and geolocation signals, and ongoing monitoring. EURSAFO and EUTBL sit in a similar bucket as euro-denominated Reg S wrappers, accessible to non-U.S. persons but closed to U.S. retail.
Reg S products also come with a lock-up. Tokens bought under Reg S cannot be resold into the U.S. or to U.S. persons for a defined period, which is why some of these tokens have different transfer rules depending on where the holder sits. If you are a non-U.S. person holding USDY on Solana and you sell to a U.S. person, that U.S. person is buying restricted securities and may not be able to redeem through the issuer.
The third tier most readers miss: qualified purchasers
Accredited is the floor. A second, smaller tier sits above it. Under Section 2(a)(51) of the Investment Company Act, a qualified purchaser is an individual or family office with at least $5 million in investments, or an entity with at least $25 million in investments. Funds that rely on this exemption, sometimes called 3(c)(7) funds, can only accept money from qualified purchasers.
This matters because some of the larger tokenized private credit and treasury vehicles are structured as 3(c)(7) funds. Their smart contracts are gated to a smaller whitelist, and the issuer's documentation names qualified-purchaser thresholds for private funds as the binding test. An accredited investor with $1.5 million in net worth is shut out. The product is real, the on-chain venue is real, but the eligibility line is drawn higher than most marketing pages admit.
The practical effect is that "RWA" is not a single market. It is at least three nested markets, each with its own buyer pool: 506(c) accredited, 3(c)(7) qualified purchaser, and Reg S non-U.S. person. A given token is usually only accessible to one of the three, sometimes two with a token split, and the rules are enforced both off-chain by the transfer agent and on-chain by the contract's whitelist.
Where the actual friction sits
Most of the friction in buying a tokenized treasury is not the on-chain transfer check. It is everything that has to happen before a wallet is allowed onto the whitelist in the first place.
Identity and accreditation verification
For a 506(c) product, the user submits government ID, proof of address, a self-certification of accredited status, and supporting documents such as tax returns, brokerage statements, or a CPA letter. The verification vendor cross-checks the documents and either approves or rejects the application. This step can take days, and a rejected application has no on-chain footprint.
For Reg S products, the user submits identity documents and a non-U.S. person attestation. Geolocation, IP reputation, and document country are cross-checked. A U.S. passport holder living in Singapore is still treated as a U.S. person for Reg S purposes, which surprises a lot of users.
Wallet binding and Sybil-resistant whitelisting
Once the user is approved, the issuer or transfer agent signs a message that adds the user's wallet address to the on-chain whitelist. From that point on, the contract refuses to transfer tokens to or from any address that is not on the list. This is the AVC, or allowlist-controlled contract, pattern, and it is what makes the gating Sybil-resistant at the smart-contract level. A user cannot bypass it by generating a fresh wallet.
The same logic protects the issuer from sanctions risk. Address screening against OFAC and EU lists runs continuously, and a wallet that becomes sanctioned mid-life will be removed from the whitelist and unable to redeem. Holders in restricted jurisdictions are usually asked to redeem and exit before that happens, with the issuer bearing the operational cost.
Jurisdictional rules that override the technology
The smart contract does not know what country the user is in. The issuer does. That is why jurisdictional rules are layered on top of the whitelist. A non-U.S. person can hold USDY on Solana but cannot hold BUIDL on Ethereum, because BUIDL is a 506(c) product with no Reg S tranche. A U.S. accredited investor can hold BUIDL but not USDY under Reg S. A qualified purchaser can hold either, plus the 3(c)(7) private credit vehicles that the accredited tier cannot touch.
The on-chain venue matters less than the issuer's documentation. Avalanche, Arbitrum, Solana, and Ethereum are all just rails. The rules live in the offering memorandum and the transfer agent's policy.
Can a non-U.S. user ever hold a U.S. RWA token
Yes, and this is where the picture gets more useful for a crypto-native audience outside the United States. A non-U.S. person can hold a Reg S product like USDY, EURSAFO, or EUTBL, and a non-U.S. person who is also a qualified purchaser can additionally hold some 3(c)(7) vehicles. The path is: complete KYC with the issuer, attest non-U.S. status, get the wallet whitelisted, subscribe through the issuer's primary issuance flow, then optionally trade on supported venues.
The harder case is the U.S. user who is not accredited. They are locked out of every 506(c) product by design and are also locked out of every Reg S product because they are a U.S. person. The only on-chain U.S. Treasury exposure available to them is the public market: a registered tokenized treasury product, a treasury ETF wrapper, or a publicly offered money-market fund token. The RWA sector is actively building these public products, and they will look very different from BUIDL or OUSG once they land, because they will not need a whitelist.
One more wrinkle: tokenized treasury products are not interchangeable with stablecoins. USDY pays a yield and is a security, which is why it is gated. USDC is a stablecoin and is not. Users sometimes confuse the two because both sit on Ethereum, Arbitrum, and Solana, but they sit under completely different regulatory regimes. Treating a yield-bearing RWA token as if it were a stablecoin is one of the more common mistakes in this corner of the market.
How MiCA changes what's available in the EU
MiCA, the EU's Markets in Crypto-Assets regulation, came into full effect in 2024 and reshapes the European RWA landscape. Under MiCA, asset-referenced tokens and e-money tokens have a defined regime, and tokenized securities fall under existing MiFID II rules. For an EU user, this means the gating stack looks familiar, KYC and accreditation where required, but the legal source of the rules is European rather than U.S.
In practice, this has opened space for EU-domiciled tokenized treasury and money-market products that are accessible to EU retail under a fully registered wrapper. EURSAFO and EUTBL sit in this broader category of euro-denominated treasury exposure, although their distribution rules still depend on whether they are structured as Reg S, MiCA-registered, or both. A product that is simultaneously Reg S and MiCA-registered has to satisfy both rule sets, which is why the documentation for these products is unusually long.
The flip side is that MiCA has not made tokenized U.S. Treasuries freely available to EU retail. A EU retail user still cannot buy BUIDL or OUSG without going through the issuer's KYC and qualifying under the relevant exemption. MiCA changes the menu of EU-domiciled products, not the eligibility rules for U.S.-domiciled ones. Crypto-native users in the EU who assumed MiCA would unlock the entire global RWA market have been surprised to learn that it mostly unlocks EU-issued products.
The risks that don't show up in the marketing
Risk-first, because this is where most of the actual money gets lost. The gating stack is doing real work, and when it fails or is misunderstood, holders can end up holding restricted tokens they cannot redeem.
The first risk is jurisdictional mismatch. A U.S. user who receives USDY through a peer-to-peer transfer from a non-U.S. person holds restricted securities. The contract will not let them redeem, because they are not on the whitelist as a U.S. person, and the issuer has no obligation to help. The tokens remain in the wallet but are economically stranded.
The second risk is whitelist removal. If sanctions screening flags an address, or if the user fails to refresh their KYC on the issuer's schedule, the address is removed from the whitelist and redemption is paused until the issue is resolved. Several issuers run annual refresh cycles, and a user who ignores the email finds their tokens frozen.
The third risk is product tier confusion. A user who qualifies as accredited but not as a qualified purchaser can be shut out of higher-tier funds without realizing it, and the marketing page rarely highlights which tier is required. Reading the offering memorandum is the only reliable check.
The fourth risk is platform risk on top of issuer risk. Holding BUIDL on a centralized exchange that is itself a sanctioned entity creates a layered problem: the issuer's whitelist approves the exchange's omnibus wallet, but the user's beneficial ownership inside that wallet is a separate record that can break. The cleanest setup is always direct wallet holding with the user's own whitelist entry.
The fifth risk is lock-up and resale restrictions. Reg S tokens cannot be resold to U.S. persons during the restricted period. A non-U.S. person who sells to a U.S. person on a DEX has technically violated the resale rules, and the U.S. buyer's redemption rights are unclear. Smart-contract permission does not equal legal permission.
Practical implications for a crypto-native user
For a user trying to actually buy a tokenized treasury, the workflow is closer to opening a brokerage account than to swapping on Uniswap. You pick a product, complete the issuer's KYC and accreditation check, get your wallet whitelisted, subscribe through the issuer's primary issuance flow, receive the tokens at the whitelisted address, and then hold or trade them only within the rules of the relevant exemption.
Choosing a venue is mostly a question of where the product is natively issued and where secondary liquidity is deepest. BUIDL is natively on Ethereum with growing presence on Arbitrum and other supported chains. OUSG sits on Ethereum. USDY spans Arbitrum, Solana, and other chains. JTRSY and USTB are Ethereum-native. EURSAFO and EUTBL are euro-denominated and live where their issuer supports them. The chain is a logistical choice. The gating rules are not.
For a U.S. retail user, the realistic path to on-chain Treasury exposure today runs through registered, non-whitelisted products as they come to market, and through the existing treasury ETF wrappers. The whitelist-gated funds are not accessible, and there is no smart-contract workaround. For a non-U.S. person, the Reg S products are genuinely open once KYC is complete. For an EU retail user, MiCA-registered EU-domiciled products are the cleanest option. The on-chain RWA market is real, but it is not yet the permissionless market its branding suggests.
How to follow tokenized treasuries the smart way
Tokenized treasuries move on three signals at once: product launches, regulatory shifts, and on-chain liquidity. Product launches change which funds are available. Regulatory shifts, including SEC guidance, MiCA implementation, and stablecoin rules, change who can hold them. On-chain liquidity changes how cheaply a user can move in and out. Tracking all three manually is a losing game. Zippfeed surfaces RWA headlines with sentiment scoring, bullish, neutral, or bearish, and an importance rating, so you can see which events actually move the market and which are noise.

 CoinDesk
 TheBlock
 Crypto News